Articles in this Volume

Research Article Open Access
The Rubik's Cube Group: Structure, Commutators, and Algebraic Solving Strategies
The Rubik's Cube was invented by Ernő Rubik as a toy and has long served as a fertile ground for mathematical inquiry, particularly within finite group theory. This natural correspondence between a tangible puzzle and an abstract algebraic structure bridges intuition and formalism, establishing cube groups as canonical examples in both pedagogical and research-oriented algebra. Over the past five decades, extensive research has been devoted to understanding the group-theoretic structure of the Cube. Early investigations established the algebraic decomposition of cube groups via semidirect products, while subsequent work explored generators and relations, the diameter of the Cayley graph, and configuration enumeration. More recently, representation theory and the commutator structure of cube groups have emerged as frontiers, with significant results on minimal representation dimensions and the proof that every element of the commutator subgroup is itself a single commutator. The present paper surveys these group-theoretic foundations underlying Rubik's Cube modeling and solving strategies. It recapitulates essential preliminaries and then focuses on two complementary modelling approaches: the first employs linear algebra and permutation group theory to develop a mathematical reduction model, and the second examines the specific role of commutators in blindfolded solving. The paper concludes with a discussion of future research directions.
Show more
Read Article PDF
Cite
Research Article Open Access
A Benchmark of Unsupervised Anomaly Detectors for Credit Card Fraud under Two Training Protocols
Article thumbnail
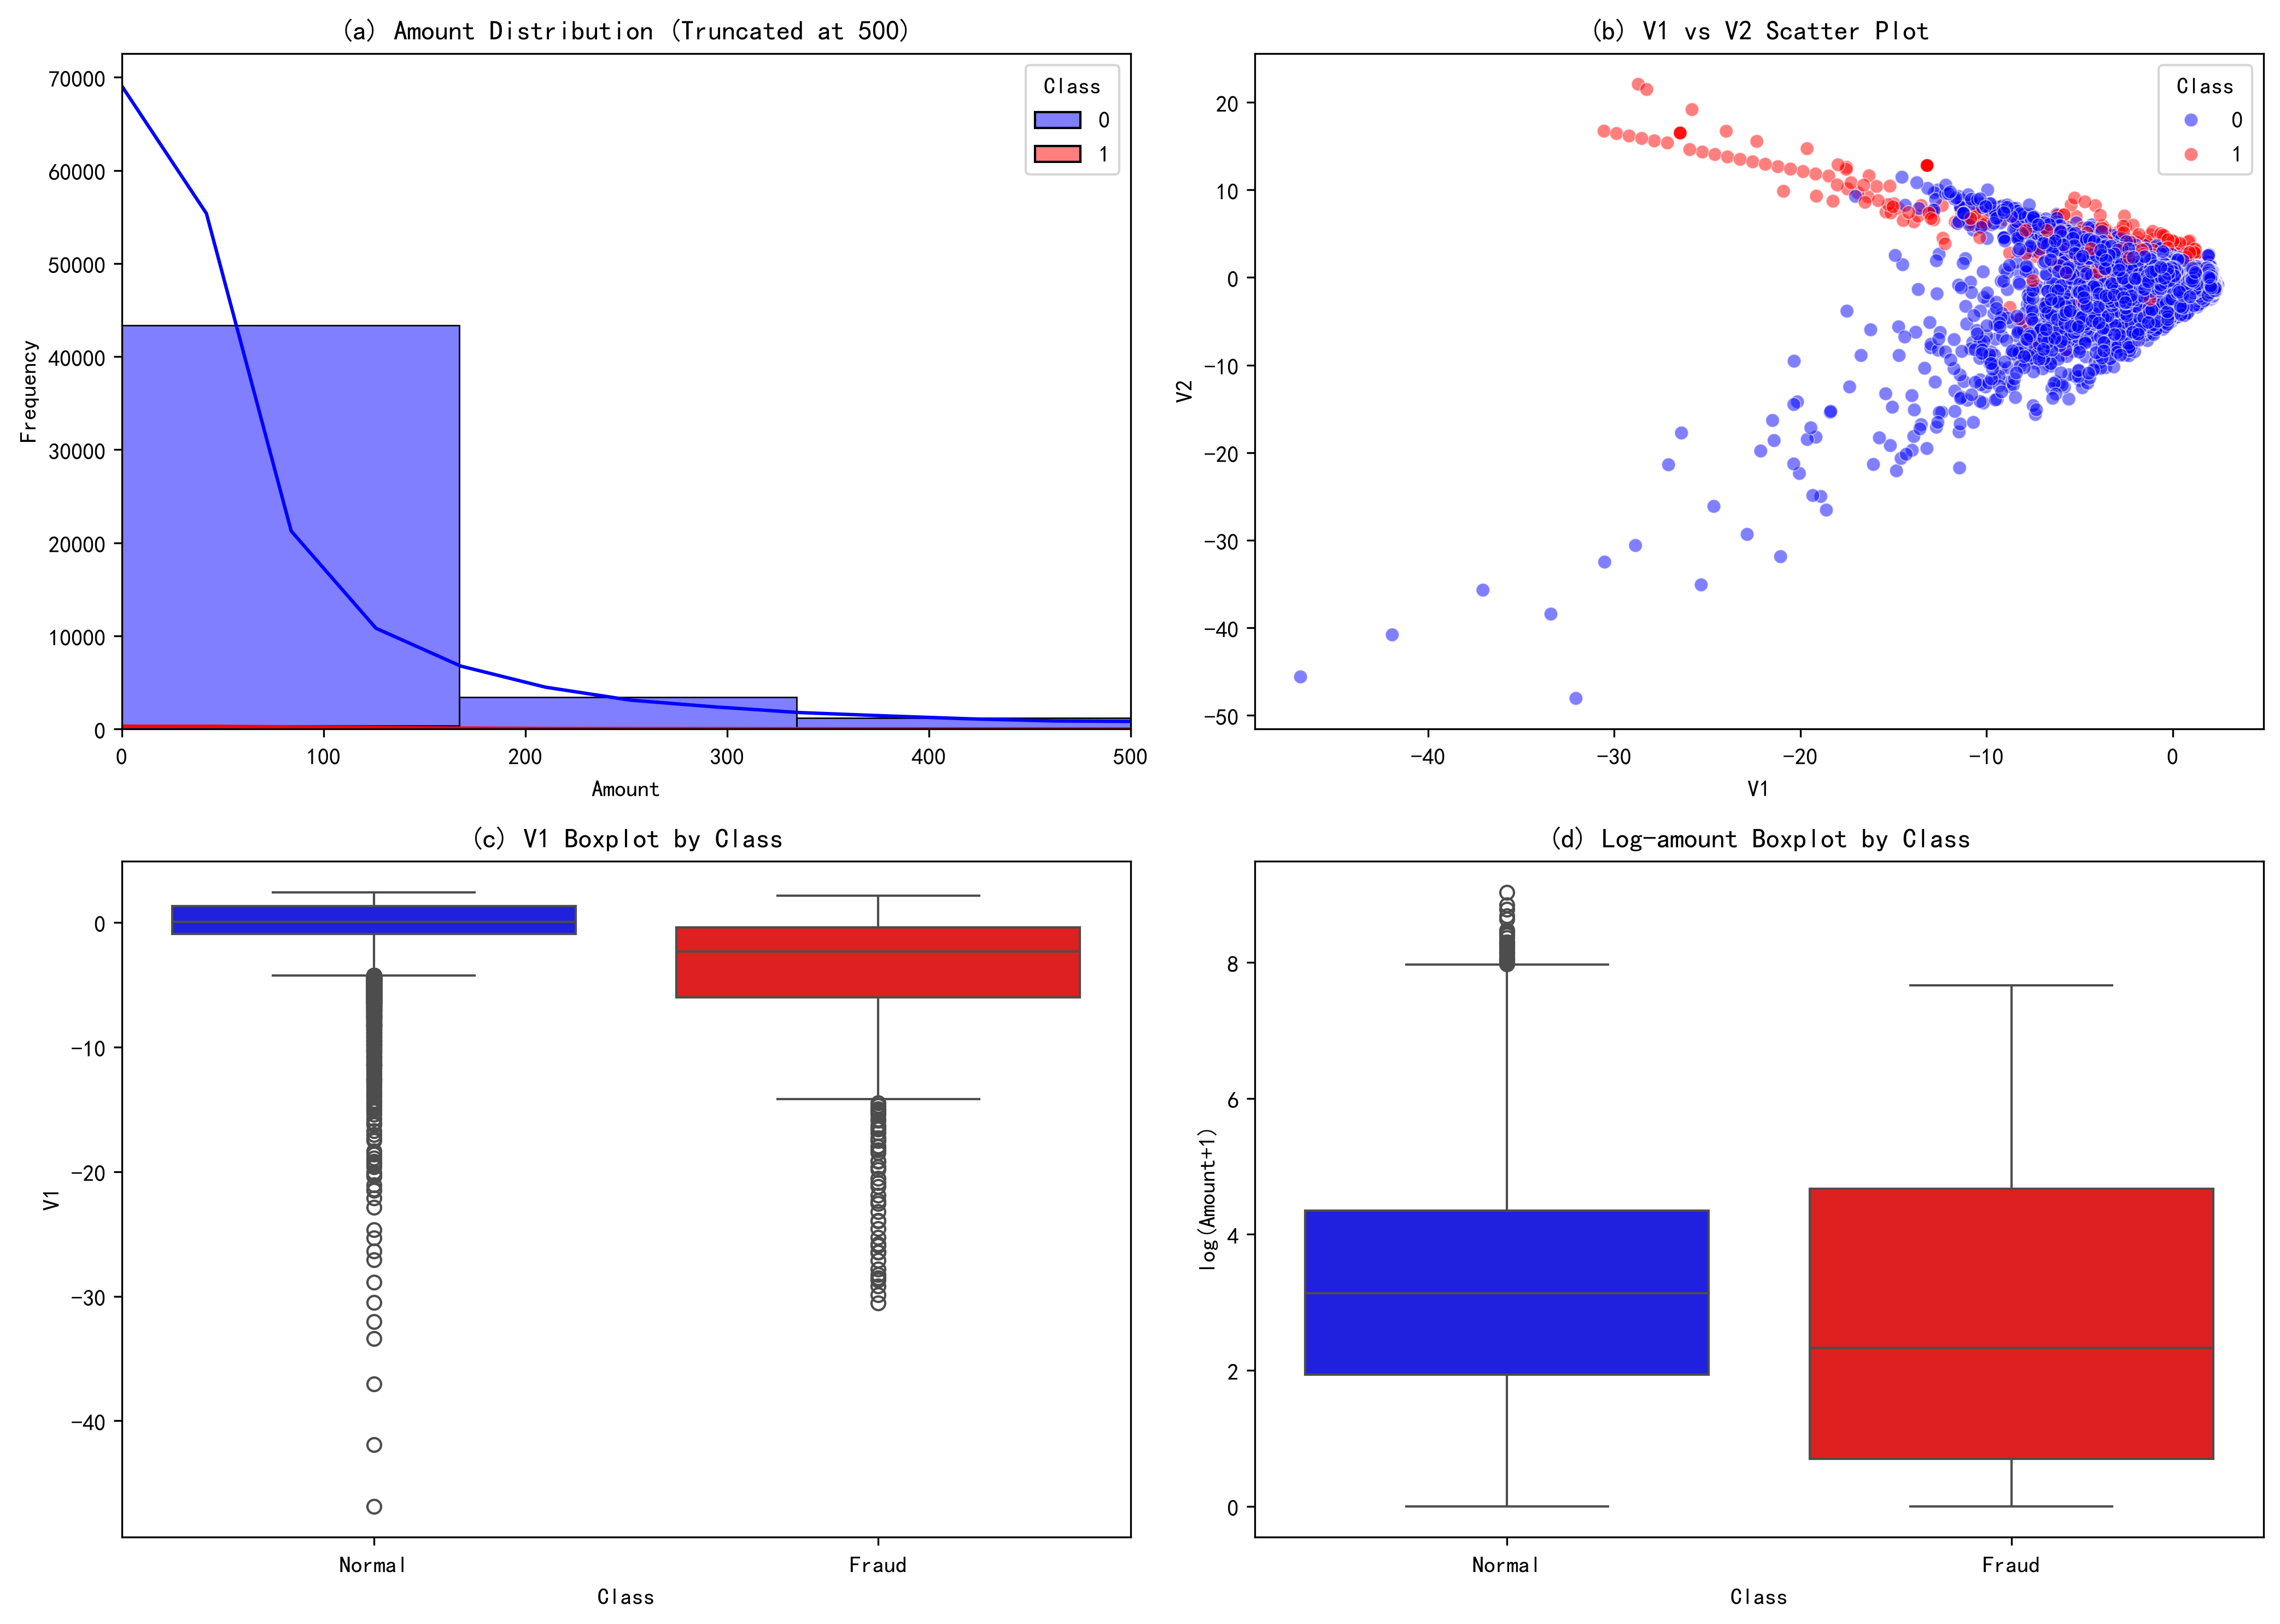
Credit card fraud detection is a critical problem in financial security, yet real-world deployment scenarios often lack labeled fraud samples at initial stages, making unsupervised anomaly detection an appealing approach. However, the comparative performance of different unsupervised detectors under varying training data compositions—whether trained exclusively on normal transactions or on mixed data containing unlabeled frauds—remains insufficiently studied. This paper presents a head-to-head benchmark of five unsupervised anomaly detectors—Mahalanobis distance, Isolation Forest, Local Outlier Factor (LOF), One-Class SVM, and Elliptic Envelope—on the publicly available ULB Credit Card Fraud Detection dataset. Each detector is evaluated under two training protocols: novelty detection (trained solely on normal transactions) and outlier detection (trained on the full dataset containing both normal and fraudulent samples). Performance is measured using PR-AUC, Precision@k, and recall at low false positive rates. Results show that Mahalanobis distance and LOF achieve strong performance under the novelty detection protocol (PR-AUC > 0.73) but suffer catastrophic degradation when trained on mixed data, with PR-AUC dropping by 0.57 and 0.72 respectively. Isolation Forest gives solid and reliable results on both two tested protocols, and its PR-AUC score increases slightly from 0.3953 to 0.4432. After parameter adjustment (with parameters set as support_fraction=0.9, contamination=0.01), Elliptic Envelope gets moderate performance (PR-AUC≈0.37) and is almost insensible to protocol changes. The conclusions obtained in this part can provide actual instruction for choosing unsupervised detectors to be used in real fraud detection systems working under various conditions of label availability and data quality.
Show more
Read Article PDF
Cite
Research Article Open Access
Research on the State Transition of US Stock Prices Based on Markov Chains: A Case Study of Eight Representative US Stocks and the Nasdaq Composite Index
The U.S. stock market exhibits substantial volatility and regime‑dependent behavior, yet the transition patterns among discrete price states are not well understood. This study investigates how price state transition dynamics vary across individual stocks and industries and whether they align with the broader market index. Eight representative U.S. stocks (AAPL, MSFT, AMZN, COST, AMGN, XOM, JPM, and NEE) and the Nasdaq Composite Index (IXIC) are examined using monthly closing prices from 2018 to 2025. Monthly price movements are classified as rising, fluctuating, or falling, and a discrete time homogeneous Markov chain is used to estimate one-step and multi-step transition probabilities, steady state distributions, and persistence and reversal patterns. The results reveal clear heterogeneity across individual stocks and industry groups. Technology stocks show stronger upward state persistence, weaker flat state persistence, and stronger rebounds after declines, defensive stocks display greater flat state persistence and more moderate rebounds, while cyclical stocks generally exhibit intermediate patterns. The Nasdaq Composite evolves more smoothly than individual stocks, with more frequent transitions between rising and fluctuating states and fewer direct reversals between rising and falling states, indicating that the index cannot fully represent firm-specific dynamics. These findings extend Markov chain analysis from single assets to systematic cross-stock comparison and provide useful evidence for understanding market state evolution and supporting industry sensitive portfolio decisions.
Show more
Read Article PDF
Cite